A lot of foreigners moving to Japan ask the same question: can I just use travel insurance while I’m living here? At first glance, travel insurance can seem simpler and cheaper than joining Japan’s public health insurance system. For long-term residents, though, the difference between the two matters a great deal — and misunderstanding it can lead to real financial and legal problems.
This guide explains what each type of insurance actually covers, which one applies to your situation, and when it makes sense to combine public insurance with a private plan.
- What Is Travel Insurance?
- What Is Health Insurance in Japan?
- The Core Difference
- Can Foreigners Use Travel Insurance Instead of Japanese Health Insurance?
- Why Travel Insurance Often Isn’t Enough for Long-Term Stays
- When Travel Insurance Does Make Sense
- The Best Approach for Long-Term Residents
- Recommended Insurance by Situation
- How Much Does Japanese Health Insurance Cost?
- Common Mistakes to Avoid
- Frequently Asked Questions
- Related Guides
What Is Travel Insurance?
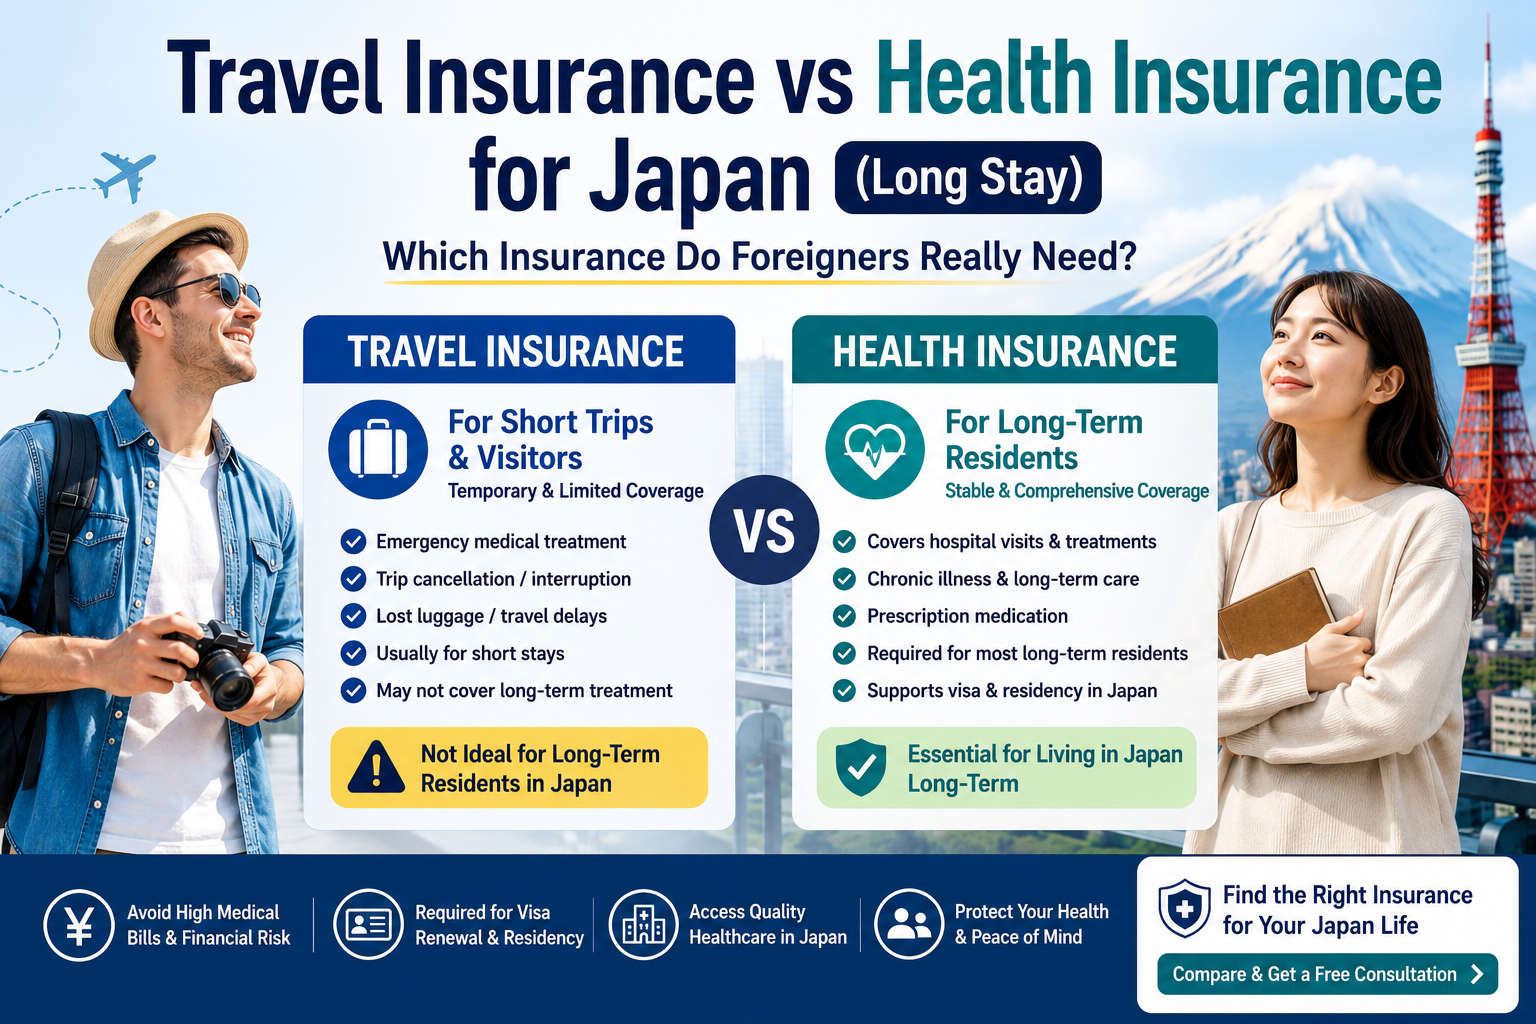
Travel insurance is temporary coverage designed for tourists, short-term travelers, and business trips. It typically covers emergency medical treatment, trip cancellation, lost luggage, flight delays, and emergency evacuation. It’s built around short stays abroad, not ongoing residency.
What Is Health Insurance in Japan?
Health insurance in Japan refers to one of two public systems: National Health Insurance (NHI) or Employees’ Health Insurance (Shakai Hoken). These are designed for residents, workers, students, and long-term visa holders — not short-term visitors. They cover hospital visits, surgeries, prescription medication, and ongoing medical treatment, with patients generally paying about 30% of covered costs.
The Core Difference
| Feature | Travel Insurance | Japanese Health Insurance |
|---|---|---|
| Designed for tourists | Yes | No |
| Designed for residents | No | Yes |
| Long-term coverage | Limited | Yes |
| Covers chronic conditions | Often limited | Yes |
| Required for residents | No | Usually yes |
| Relevant to visa/residency status | Limited | Important for long-term residency |
| Monthly premium | Usually fixed | Based on income or salary |
Can Foreigners Use Travel Insurance Instead of Japanese Health Insurance?
For short stays, sometimes. For long-term residents, usually not. If you’re staying in Japan longer than three months as a registered resident, you’re generally expected to enroll in one of Japan’s public insurance systems — this applies to students, workers, freelancers, dependents, and long-term residents alike.
Why Travel Insurance Often Isn’t Enough for Long-Term Stays
This is where a lot of foreigners run into trouble. Travel insurance policies commonly:
- Expire after a set period (often 30, 90, or 180 days)
- Exclude ongoing or chronic conditions
- Reject pre-existing conditions entirely
- Limit which hospitals you can use
- Offer weaker support once you’ve established residency
Some policies even become invalid once you register as a resident in Japan, since they’re not designed for that situation at all.
Coverage expiration
Long-term visa holders relying on a travel policy that expires after a few months can suddenly find themselves without any coverage at all, often without realizing it until they need care.
Chronic illness exclusions
Travel insurance is built around emergencies, not ongoing care. Conditions like diabetes, asthma, mental health treatment, or long-term rehabilitation are often not fully covered, if at all.
Residency and visa considerations
Japan increasingly checks health insurance enrollment as part of visa renewals and residency-related processes. Not being enrolled in public insurance can create friction during these reviews. For more on this, see: What Happens If Foreigners Don’t Have Health Insurance in Japan?
Large medical bills
Without proper health insurance, foreigners may be responsible for the full cost of hospitalization, surgery, or emergency treatment — costs that can add up quickly.
When Travel Insurance Does Make Sense
Travel insurance remains genuinely useful for tourists, short-term language school students, temporary business trips, and anyone staying less than three months. It’s well-suited to covering emergency evacuation, lost baggage, and general travel disruptions during a short trip. For a full comparison of providers, see: Best Travel Insurance for Foreigners Visiting Japan
The Best Approach for Long-Term Residents
For most long-term residents, the most reliable strategy is public insurance as the required foundation, plus optional private insurance for the gaps public coverage doesn’t fill — better English-language support, cashless hospital access, or higher reimbursement limits. See: National Health Insurance vs Private Insurance in Japan
Recommended Insurance by Situation
| Situation | Recommended Insurance |
|---|---|
| Tourist / short-term visitor | Travel insurance |
| Student visa (long-term) | National Health Insurance, optionally with private insurance |
| Work visa | Employees’ Health Insurance, optionally with private insurance |
| Freelancer | National Health Insurance, optionally with private insurance |
| Long-term / permanent resident | Public insurance plus more comprehensive private coverage |
How Much Does Japanese Health Insurance Cost?
As a general guide:
- Students and lower-income residents: roughly ¥2,000–¥15,000/month
- Employees: based on salary, generally deducted automatically
- Freelancers with moderate income: roughly ¥15,000–¥30,000+/month
- Private insurance add-on: roughly ¥2,000–¥8,000+/month depending on coverage
For a full cost breakdown, see: How Much Does Health Insurance Cost in Japan for Foreigners?
Common Mistakes to Avoid
- Assuming travel insurance covers everything. It usually doesn’t, once you’ve settled into long-term residency.
- Delaying public insurance enrollment. This can lead to retroactive premium billing and complications later, not just a delay-free pass.
- Choosing insurance based on price alone. The cheapest plan often comes with significant coverage limitations that only become apparent when you actually need care.
Frequently Asked Questions
Can I use travel insurance while studying in Japan short-term? For very short programs, possibly. Long-term students are generally expected to enroll in National Health Insurance instead.
Is Japanese health insurance mandatory? For most long-term residents, yes — once you register a residence and stay beyond three months.
Does travel insurance cover regular hospital visits during a long stay? Usually not as comprehensively as resident health insurance, and coverage often lapses well before a long-term stay would end.
Can foreigners purchase private insurance in Japan? Yes — many insurers offer plans specifically designed for foreign residents, which can be added on top of required public insurance.
Related Guides
- What Insurance Do Foreigners Need in Japan?
- Health Insurance for Foreign Workers in Japan
- What Happens If Foreigners Don’t Have Health Insurance in Japan?
Note: Premium figures in this article are general estimates. Actual costs depend on your income, municipality, and specific plan. Confirm exact figures with your municipal office, employer, or insurance provider directly.