A lot of foreigners moving to Japan wonder the same thing: what actually happens if I just don’t enroll in health insurance? Some assume they can save money by skipping it — especially students, freelancers, or those only planning to stay a year or two.
In practice, going without insurance in Japan tends to create bigger financial problems than it solves. This guide walks through what’s actually required, what happens if you remain uninsured, and why even healthy foreigners are generally better off enrolling.
- Is Health Insurance Mandatory in Japan?
- What Actually Happens If You Don’t Enroll
- Why Some Foreigners Skip Insurance Anyway
- Is Travel Insurance Enough Instead?
- What If You’re Self-Employed or Freelancing?
- Can Hospitals Refuse Treatment If You’re Uninsured?
- Why Some Residents Add Private Insurance Too
- Frequently Asked Questions
- Related Guides
- Final Thoughts
Is Health Insurance Mandatory in Japan?
Yes. Foreign residents staying in Japan for more than three months are generally required to enroll in either National Health Insurance (NHI / Kokumin Kenko Hoken) or Employees’ Health Insurance (Shakai Hoken), depending on their employment situation. Japan operates a universal healthcare system — enrollment isn’t optional once you’ve registered as a resident.
This applies broadly to students, workers, freelancers, dependent visa holders, and long-term residents alike.
What Actually Happens If You Don’t Enroll
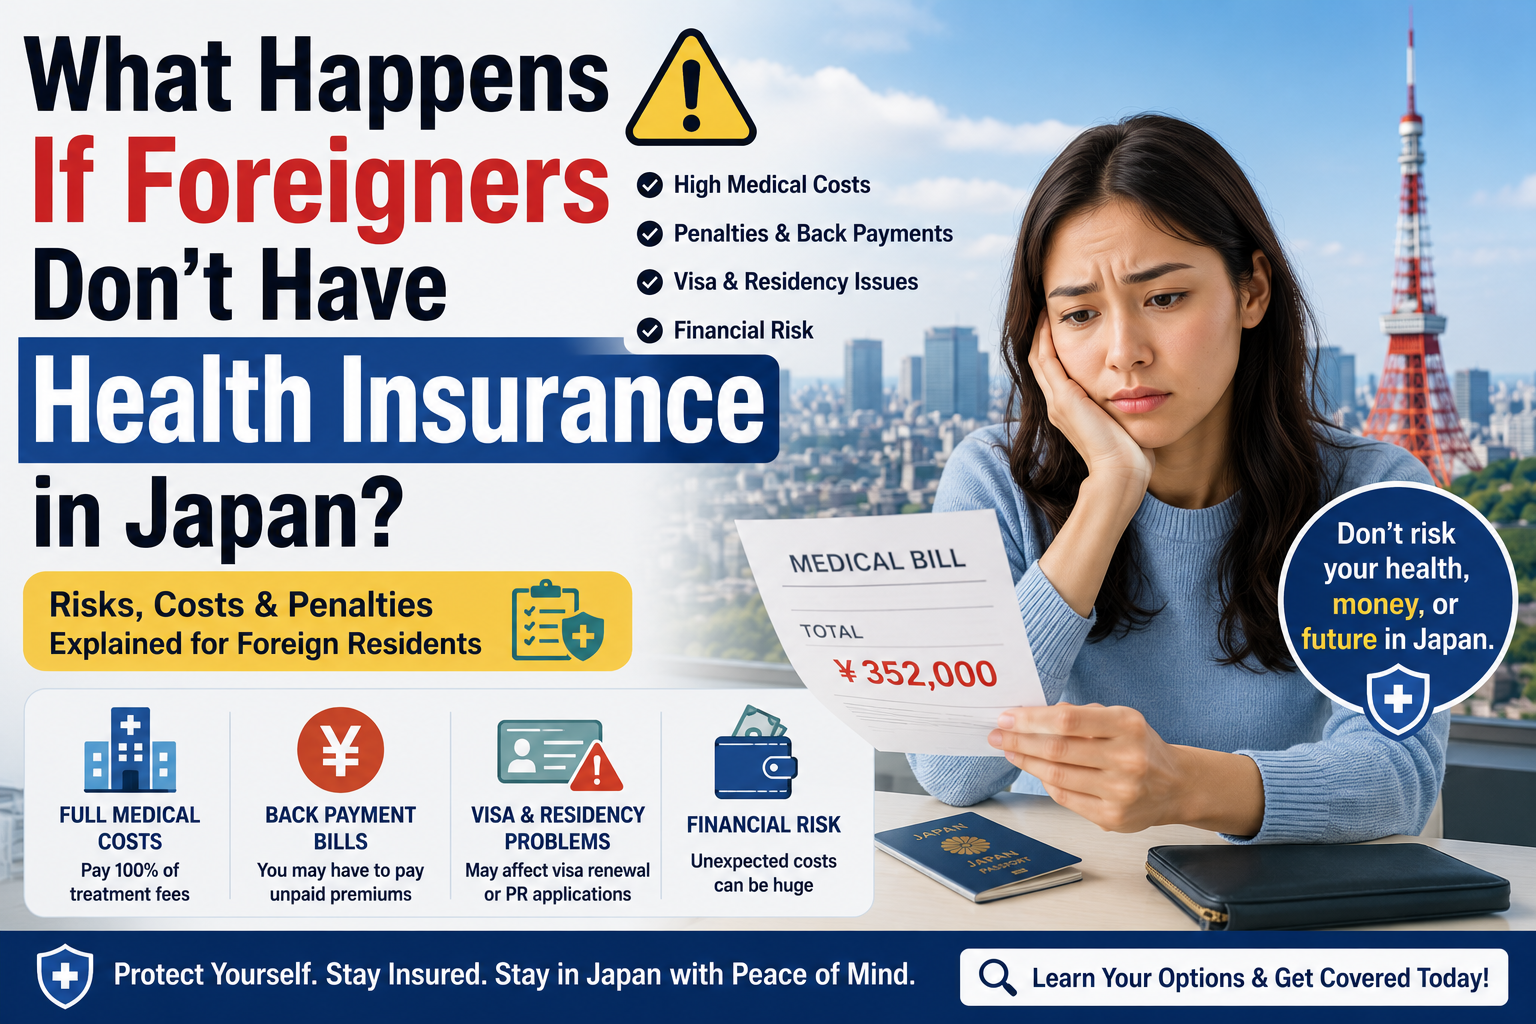
1. You’re responsible for 100% of medical costs
This is the most immediate risk. Without insurance, you pay the full cost of:
- Hospital fees
- Surgery
- Prescription medication
- Emergency treatment
Public insurance normally covers around 70% of these costs. Without it, that entire burden falls on you, and Japanese medical care — while high quality — isn’t cheap when paid out of pocket.
Rough cost examples without insurance:
| Treatment | Approximate Cost Without Insurance |
|---|---|
| Basic clinic visit | ¥5,000–¥15,000 |
| MRI scan | ¥40,000–¥100,000 |
| Emergency room visit | ¥20,000–¥80,000+ |
| Hospitalization (per stay) | Several hundred thousand yen |
| Surgery | ¥500,000+ possible |
These figures are general estimates for illustration and vary by hospital, region, and treatment complexity. They are not a quote for any specific procedure.
Even a single accident or short illness can turn into a serious financial setback if you’re uninsured.
2. You may be billed retroactively
This surprises a lot of people. If your municipal office determines you should have been enrolled earlier and weren’t, you’re generally not let off the hook — you’ll typically be required to enroll immediately and pay premiums retroactively for the period you should have been covered.
For example: if you lived in Japan for two years without enrolling in NHI, your city office may later require two years of unpaid premiums, sometimes alongside administrative charges. For long-term residents who put this off, the total can add up to a substantial, unexpected bill.
3. It can complicate visa and residency matters
Japan increasingly checks whether foreign residents are properly enrolled in health insurance, pension contributions, and taxes as part of visa renewals and residency-related applications. Gaps in your insurance history can raise questions during these processes — this matters especially for work visa holders and anyone planning to apply for permanent residency down the line.
This isn’t automatically disqualifying, but it’s the kind of administrative loose end that’s much easier to avoid than to explain after the fact.
4. Medical care becomes more stressful, not just more expensive
Japan’s healthcare system is excellent, but hospitals generally expect patients to be able to pay. Without insurance:
- Routine and emergency care both become significantly more expensive
- Some clinics may be hesitant to take on uninsured patients, or request large upfront payments
- Navigating an already unfamiliar system becomes harder when you’re also worrying about the bill
Why Some Foreigners Skip Insurance Anyway
Common reasons people end up uninsured aren’t usually deliberate risk-taking — they’re more often:
- Wanting to save money in the short term
- Not fully understanding how the system works
- Assuming they’re healthy enough that it doesn’t matter
- Believing travel insurance already covers them
- General confusion about municipal office procedures
The problem is that these reasons tend to create larger financial exposure later, not less.
Is Travel Insurance Enough Instead?
Usually not, if you’re living in Japan long-term. Travel insurance is designed for short trips and typically:
- Has a limited coverage period
- Often excludes pre-existing conditions
- Doesn’t satisfy Japan’s residency-based insurance requirements
- Offers weaker protection for ongoing or long-term care
If you’re staying in Japan as a resident rather than a short-term visitor, public insurance enrollment is generally what’s expected, not travel insurance. For more on this distinction, see our guide: Travel Insurance vs Health Insurance for Japan (Long Stay).
What If You’re Self-Employed or Freelancing?
Freelancers and self-employed foreigners generally enroll in National Health Insurance through their local city or ward office. This is a common area where people end up accidentally uninsured — simply because the process isn’t automatic the way employer-based insurance is, and it’s easy to assume someone else is handling it.
Can Hospitals Refuse Treatment If You’re Uninsured?
In genuine emergencies, hospitals in Japan generally provide treatment regardless of insurance status. That said:
- You remain fully responsible for payment
- Some clinics may be more hesitant to schedule non-emergency treatment for uninsured patients
- Large upfront payments are sometimes requested before non-emergency procedures
Being insured doesn’t just reduce cost — it generally makes the entire experience of seeking care in Japan smoother.
Why Some Residents Add Private Insurance Too
Even people properly enrolled in public insurance often add private coverage for things public insurance doesn’t fully address — extended hospital stays, income protection during recovery, or English-language support during treatment. Public insurance is the required foundation, but for some residents it isn’t the full picture of what they want covered. See our guide on National Health Insurance vs Private Insurance in Japan for more on how the two fit together.
Frequently Asked Questions
Can foreigners use Japan’s public healthcare system? Yes. Legal residents in Japan are generally eligible to enroll in public health insurance, and in most cases are required to.
What happens if I ignore unpaid insurance premiums? Unpaid premiums can lead to retroactive billing, collection notices, and potential complications with visa or residency-related processes down the line.
Is Japanese healthcare expensive without insurance? Yes, relative to the out-of-pocket cost with coverage. Even routine treatment can be significantly more expensive when paid entirely out of pocket.
Can international students skip health insurance? Generally no — international students staying more than three months are typically required to enroll in National Health Insurance, often through their university’s guidance during orientation.
If I only just arrived, how long do I have before I need to enroll? Enrollment is generally expected shortly after you complete your residence registration at your municipal office — this isn’t something to leave for weeks or months after arrival.
Will I be notified if I’m supposed to be enrolled and I’m not? Not necessarily right away. Gaps can go unnoticed for a while, but they tend to surface during visa renewals, residency applications, or if you happen to need medical care — at which point the retroactive billing issue described above can come into play.
Does having insurance mean all my medical costs are covered? No — public insurance generally covers around 70% of standard treatment costs, with the remaining 30% paid out of pocket at the time of care. It significantly reduces your exposure, but doesn’t eliminate it entirely.
Related Guides
- What Insurance Do Foreigners Need in Japan?
- Best Health Insurance for Foreigners Living in Japan (2026 Guide)
- National Health Insurance vs Private Insurance in Japan: Which One Do Foreigners Need?
Final Thoughts
Living in Japan without health insurance carries both financial and administrative risk. The healthcare system itself is excellent and genuinely affordable once you’re covered — the risk isn’t the system, it’s the gap in coverage. For most foreigners living in Japan, enrolling in public insurance isn’t just a legal requirement; it’s one of the more straightforward financial decisions to get right early on.
Note: Cost figures in this article are general estimates for illustration purposes and vary by treatment, hospital, and region. This article is not a substitute for guidance from your municipal office regarding your specific enrollment status or obligations.