If you’re visiting Japan for tourism, business, or a short-term stay, choosing the right travel insurance can save you from serious financial trouble. Medical care in Japan is excellent — but without insurance, foreign visitors are responsible for the full cost out of pocket, and that cost can add up quickly.
This guide compares the leading travel insurance options for foreigners visiting Japan, explains what to actually look for in a policy, and helps you choose the right plan for your trip.
- Why Travel Insurance Is Essential for Japan
- What Makes a Good Travel Insurance Plan for Japan?
- Comparing Travel Insurance Providers for Japan
- Comparison Table: Travel Insurance for Japan
- How Much Does Travel Insurance for Japan Cost?
- Travel Insurance vs. Other Insurance Types
- Frequently Asked Questions
- Final Thoughts
Why Travel Insurance Is Essential for Japan
Japan does not provide free healthcare to tourists. Public insurance systems like National Health Insurance are only available to registered residents, not short-term visitors. Without travel insurance:
- You’ll typically need to pay 100% of medical costs upfront, at the time of treatment
- Emergency treatment or hospitalization can run into the hundreds or thousands of dollars
- Medical evacuation, if needed, is extremely expensive and rarely something travelers can absorb out of pocket
For more on what happens if something goes wrong without coverage, see our guide: What Happens If Foreigners Don’t Have Health Insurance in Japan?
If something does happen during your trip, see our step-by-step guide: What to Do If You Get Sick or Injured in Japan as a Tourist.
What Makes a Good Travel Insurance Plan for Japan?
Before comparing specific providers, here’s what to actually check for in a policy.
Essential coverage
- Medical expenses (a coverage limit of at least USD 100,000 is a reasonable minimum for Japan)
- Emergency hospitalization
- Prescription medication
- Ambulance and emergency transport
Strongly recommended
- Emergency evacuation and repatriation coverage
- 24/7 English-language support
- Infectious disease / COVID-19 coverage
- Cashless hospital networks, where available (this matters — see the note below)
A note on cashless treatment: Many travel insurance plans, even good ones, still require you to pay upfront and file for reimbursement afterward, rather than offering direct cashless billing at the hospital. If this matters to you, confirm it directly with the provider before purchasing — don’t assume it’s included by default.
If you’re wondering whether your credit card’s built-in travel insurance is enough on its own, see our guide: Does My Credit Card’s Travel Insurance Cover Me in Japan?.
Comparing Travel Insurance Providers for Japan
Below are commonly used providers among foreign visitors to Japan, along with what each tends to be a good fit for.
SafetyWing — Best for Flexible, Budget-Conscious Travel
Best for: Tourists, digital nomads, travelers on multi-country trips
- Affordable, straightforward daily/monthly pricing
- Simple online sign-up
- Covers COVID-19 and other infectious diseases
- Well-suited to travelers moving between multiple countries, not just a single Japan trip
Learn more about SafetyWing
The main tradeoff is limited coverage for trip cancellation compared to more traditional travel insurance policies — it’s built primarily around medical coverage rather than trip-disruption protection.
World Nomads — Best for Active and Adventure Travel
Best for: Travelers planning hiking, skiing, or other physical activities during their trip
- Strong coverage for adventure and sports-related activities, which many standard policies exclude or limit
- Higher medical coverage limits than budget-focused options
- Established, widely used provider among long-term travelers
Pricing tends to run somewhat higher than budget-focused alternatives, which reflects the broader activity coverage.
IMG — Best for Traditional, Comprehensive Coverage
Best for: Business travelers, families, and those who prefer a more traditional insurance structure
- Strong medical and evacuation coverage
- Established international insurer with a long track record
- Wide hospital acceptance
This tends to suit travelers who want a more conventional insurance product rather than a nomad-style flexible plan, though it can be less flexible for open-ended or extended trips.
Comparison Table: Travel Insurance for Japan
| Provider | Medical Coverage | Evacuation | COVID Coverage | Price Range |
|---|---|---|---|---|
| SafetyWing | Up to $250,000 | Included | Included | Low |
| World Nomads | $100,000+ | Included | Included | Medium |
| IMG | $100,000+ | Included | Limited | Medium–High |
Coverage details and pricing change periodically — always confirm current terms directly with the provider before purchasing.
How Much Does Travel Insurance for Japan Cost?
Typical cost ranges, based on standard coverage levels:
- Short trip (7–14 days): roughly USD 10–40
- One-month stay: roughly USD 30–70
- Longer stays: costs scale with duration and depend heavily on the specific provider and coverage level chosen
Compared to the potential cost of an uninsured hospital visit in Japan, this is a small price for meaningful financial protection.
Travel Insurance vs. Other Insurance Types
Travel insurance is designed for:
- Tourists
- Business travelers
- Short-term visitors (generally under three months)
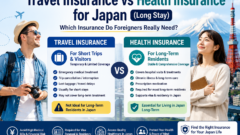
If you’re staying longer — as a student, worker, or long-term resident — travel insurance isn’t the right fit. Public insurance enrollment becomes mandatory instead. See our related guides:
- Health Insurance for Foreigners in Japan (Complete Guide)
- National Health Insurance vs Private Insurance in Japan: Which One Do Foreigners Need?
Frequently Asked Questions
Is travel insurance mandatory to enter Japan? No, it’s not a formal entry requirement for most visitors. That said, it’s strongly recommended given that uninsured medical costs are paid entirely out of pocket.
Can I buy travel insurance after I’ve already arrived in Japan? Some providers allow this, but coverage may be more limited, and pre-existing conditions or incidents that occurred before purchase typically won’t be covered. It’s best to arrange coverage before departure.
Will Japanese hospitals bill my insurance company directly? Usually not. Most travelers pay for treatment upfront and then file a claim for reimbursement afterward. A small number of providers offer cashless networks at specific partner hospitals — confirm this directly with the provider if it’s important to you.
What’s the difference between travel insurance and National Health Insurance? Travel insurance is for short-term visitors and is purchased privately before or during your trip. National Health Insurance is a public system only available to residents who have registered an address in Japan — it’s not an option for tourists.
Does travel insurance cover pre-existing medical conditions? This varies significantly by provider and plan. Many standard policies exclude pre-existing conditions, though some offer optional coverage for an additional cost. Check the specific policy’s terms before purchasing.
What should I do if I need medical care during my trip? Contact your insurance provider’s support line as soon as possible — most offer 24/7 assistance to help you locate a hospital and understand the claims process. Keep all receipts and medical documentation, as you’ll typically need them for reimbursement.
Final Thoughts
If you’re visiting Japan short-term, travel insurance isn’t a legal requirement — but given the cost of uninsured medical care, it’s a practical necessity. SafetyWing tends to offer the best balance of price and flexibility for most travelers, World Nomads is worth considering if your trip involves adventure activities, and IMG suits those who prefer a more traditional, comprehensive policy.
Note: Coverage amounts, pricing, and policy terms change over time. Always confirm current details directly with the insurance provider before purchasing.